Your Parent PLUS Consolidation Might Be Your Only Way Into IBR. Here's the Exact Path.
Student Loans, Parent PLUS, ICR to IBR
Parent PLUS loans don't normally qualify for IBR. That's the rule most advisors and borrowers know. What fewer people know is that a specific consolidation move, done at the right time, can open a path into IBR anyway. Miss the timing, and that path closes.
Here's the exact pathway, and where it breaks if you get the sequence wrong.
The Path Requires a Specific Kind of Consolidation, at a Specific Time
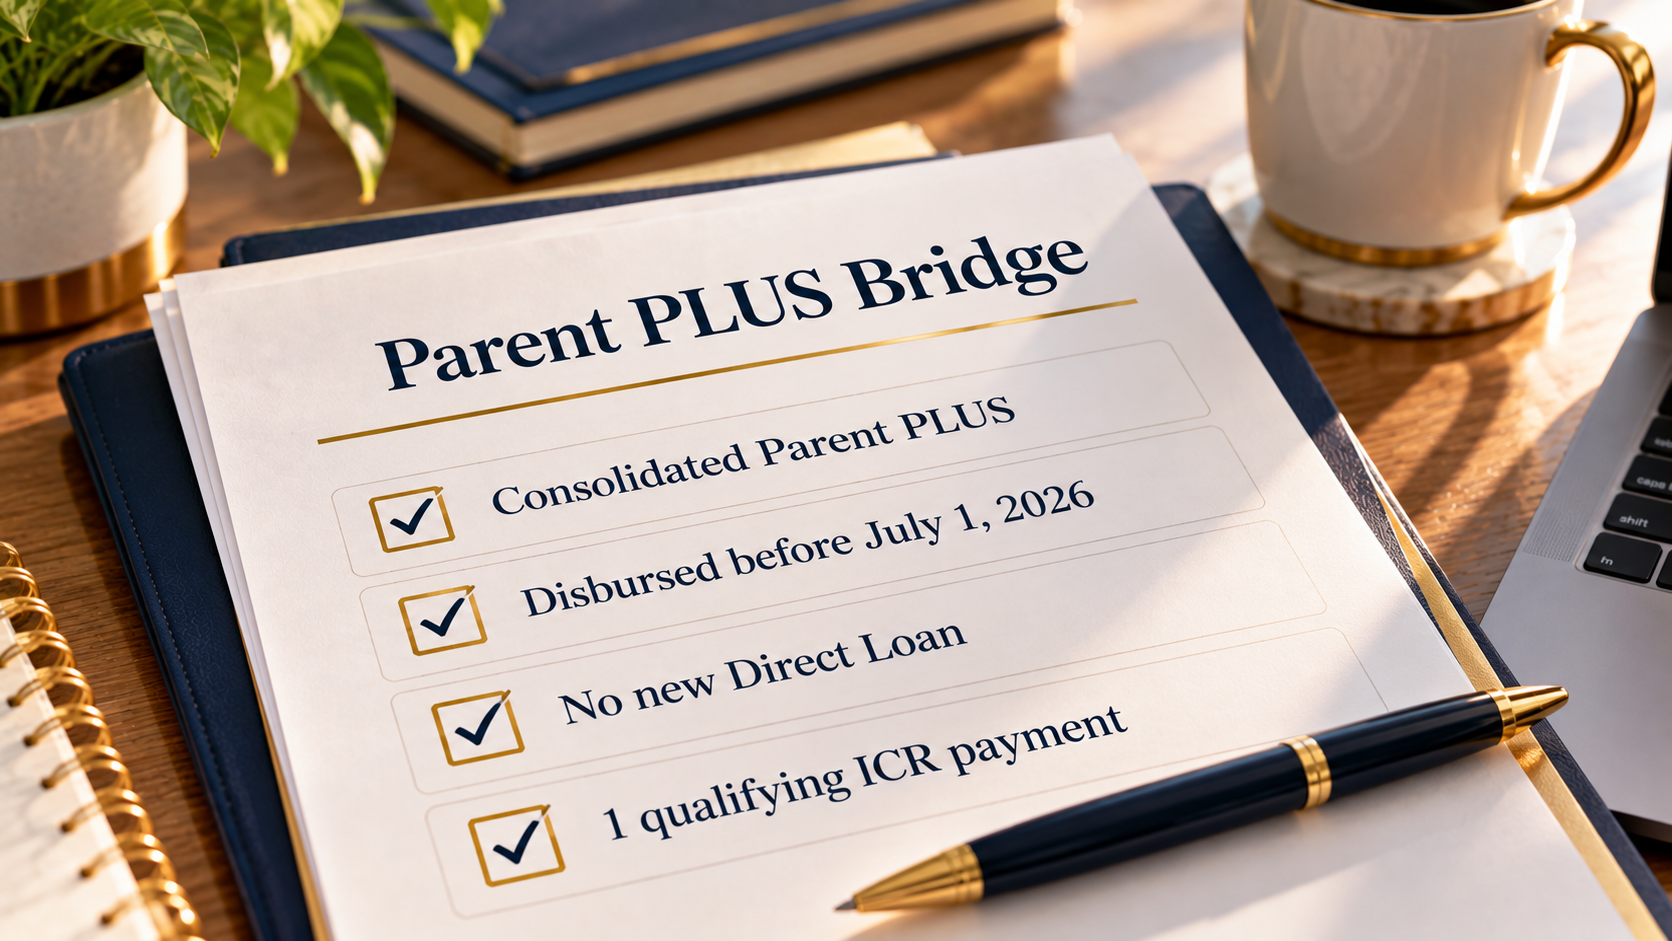
The bridge works like this: a qualifying Direct Consolidation Loan that repaid Parent PLUS debt, and that was disbursed before July 1, 2026, can preserve an income-driven repayment pathway, as long as the borrower hasn't received a new Direct Loan on or after July 1, 2026.
Once that consolidation is in place, the borrower uses ICR during the transition. After at least one qualifying IDR payment, which operationally means an ICR payment for this pathway, is made by the transition deadline, the excepted-loan treatment can allow the loan to move into IBR.
Notice how many specific conditions are stacked in that sentence. The consolidation type has to be right. The disbursement date has to be before July 1, 2026. No new Direct Loan can come in after that date. At least one qualifying ICR payment has to actually be made, and made by the transition deadline. Skip or miss any one of those, and the bridge into IBR may not be available.
ICR Is the Bridge. It Is Not the Only PSLF-Qualifying Option
A common mistake is assuming ICR is the only PSLF-qualifying plan for every borrower who consolidated Parent PLUS debt before the July 1, 2026 cutoff. It isn't. Once the bridge condition is satisfied and the loan moves into IBR eligibility, IBR becomes an option too, and IBR may fit a borrower's PSLF or forgiveness goals better than staying in ICR indefinitely.
Don't assume the first plan a Parent PLUS borrower lands in during the transition is the plan they should stay in. Confirm whether the bridge condition has been met, and re-evaluate the plan choice at that point.
PSLF Still Works Through ICR While You're Waiting
If you're a parent borrower working for a qualifying employer, ICR payments made during the transition can count as PSLF-qualifying payments. You don't have to wait until you've crossed into IBR eligibility to start accumulating PSLF credit. That's part of what makes ICR worth using here even though it typically costs more than other plans. The bridge isn't just about getting to IBR. It can also be building your PSLF clock at the same time.
A Second Date Worth Checking: July 1, 2006
Most of the transition framework revolves around 2014, 2024, 2026, and 2028. For Parent PLUS consolidation planning specifically, July 1, 2006 can also matter, though only within this narrow ICR context. If your consolidation history touches that date, confirm with your servicer whether it changes your eligibility for the ICR bridge pathway described above. This isn't a date most borrowers need to think about, but if you have older Parent PLUS debt, it's worth ruling in or out early rather than assuming it doesn't apply.
Documentation Is Not Optional Here
This pathway depends entirely on dates and payment records: when the consolidation loan was disbursed, whether the required qualifying ICR payment was actually made and processed, and whether any later Direct Loan disbursement disqualifies the borrower from the bridge. If your servicer's records don't clearly show these facts, you can lose access to a pathway you were actually eligible for, simply because you can't prove it.
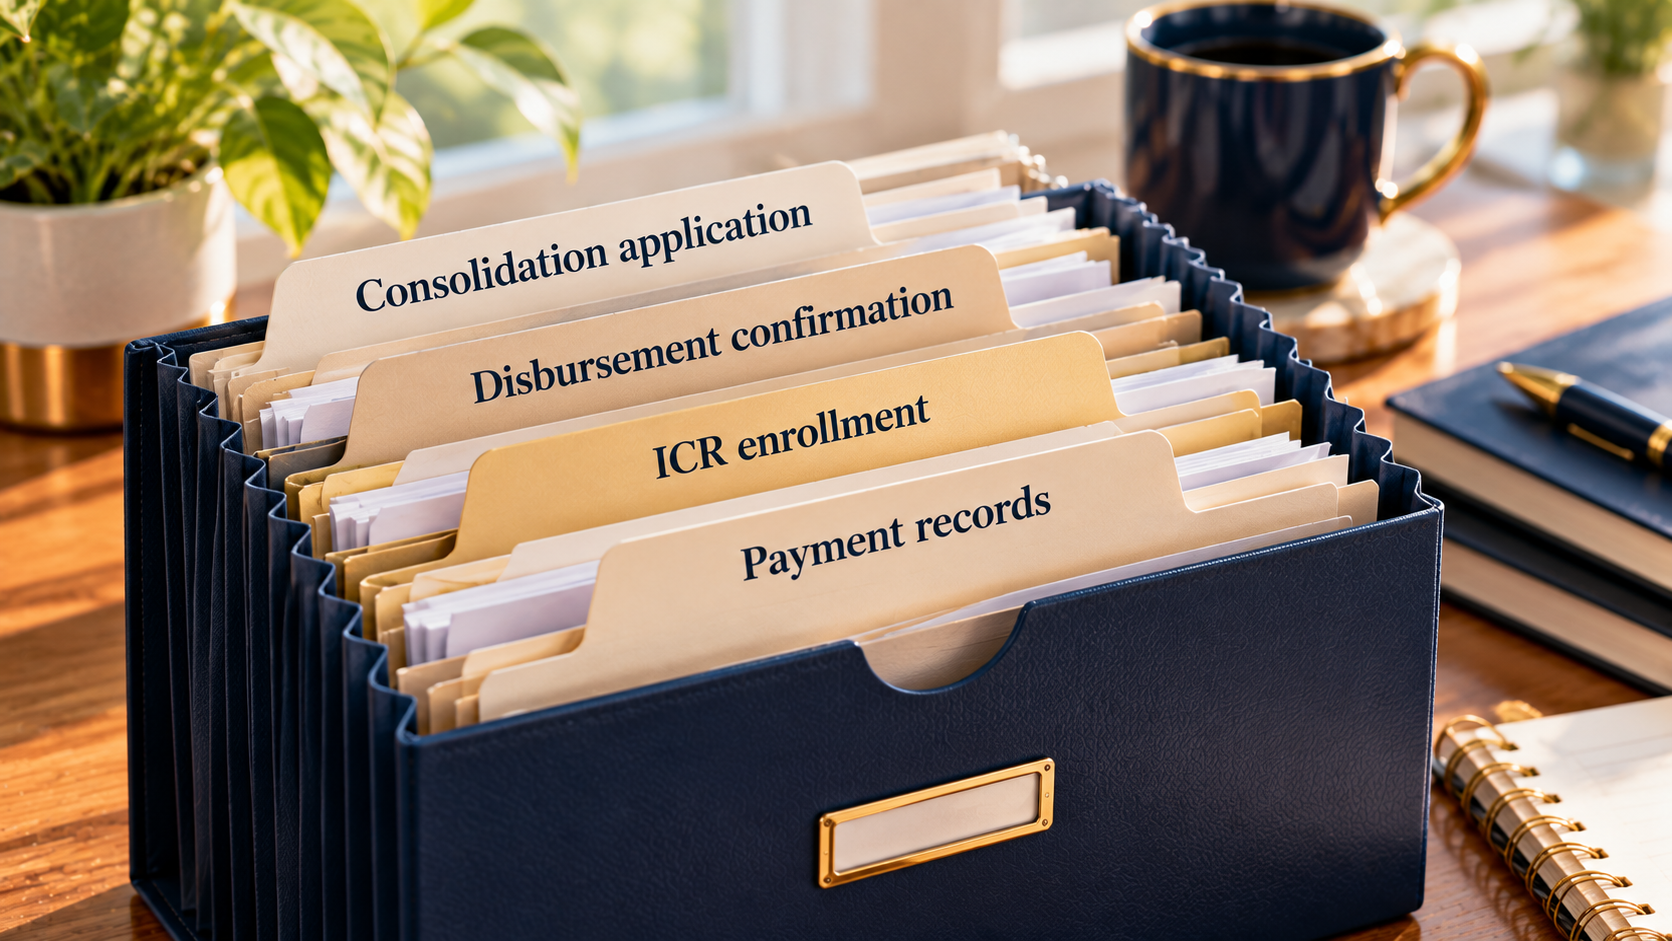
Keep the consolidation application, the confirmation of disbursement date, your ICR enrollment confirmation, and your payment records showing the qualifying payment was made and processed. If a dispute comes up later about whether you qualify for the bridge, these are the documents that resolve it.
What to Confirm Before You Assume This Path Applies to You
Confirm your consolidation loan repaid Parent PLUS debt specifically, not just any prior loan
Confirm the disbursement date on that consolidation loan was before July 1, 2026
Confirm you have not received, and do not plan to receive, a new Direct Loan on or after July 1, 2026
Confirm at least one qualifying ICR payment has been made and processed within the required transition period
Once the bridge condition is met, compare IBR against staying in ICR rather than assuming ICR is your only option
This pathway rewards borrowers who track dates and payments carefully. It punishes borrowers who assume the rule applies to them without checking every condition first.
